Skip to content
Cropped version of the official logo of Dr Krzysztof Ozimek, representing quantitative finance education and research.
  • About
  • Contact
  • Blog
  • Books
  • Multi-Method VaRCalc
  • Algorithmic Trading Models
  • QuantFin Services
Edu Hub
Cropped version of the official logo of Dr Krzysztof Ozimek, representing quantitative finance education and research.
Dr Krzysztof Ozimek
Edu Hub
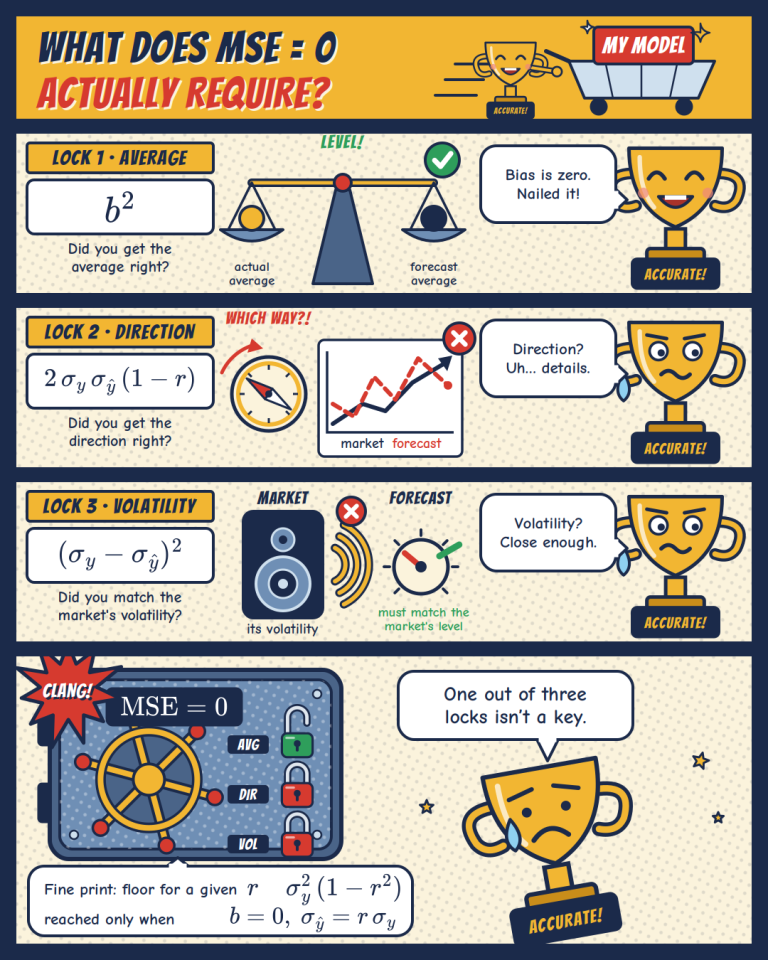
  • Comic-style infographic titled What does MSE = 0 actually require, showing three locks: Lock 1 Average with a level balance scale, Lock 2 Direction with a compass and a forecast line diverging from the market, Lock 3 Volatility with a speaker and a dial; a safe labelled MSE = 0 stays shut with only the average lock open, and a sad trophy says one out of three locks is not a key.
    Quantitative Finance

    What Does MSE = 0 Actually Require?
    Dr Krzysztof Ozimek, a Quantitative Investment & Trading Research EducatorDr Krzysztof Ozimek

    Mean squared error bundles three separate checks: bias, direction and volatility. See the MSE decomposition and why MSE reaches zero only when all three hold.
    Read More What Does MSE = 0 Actually Require?Continue

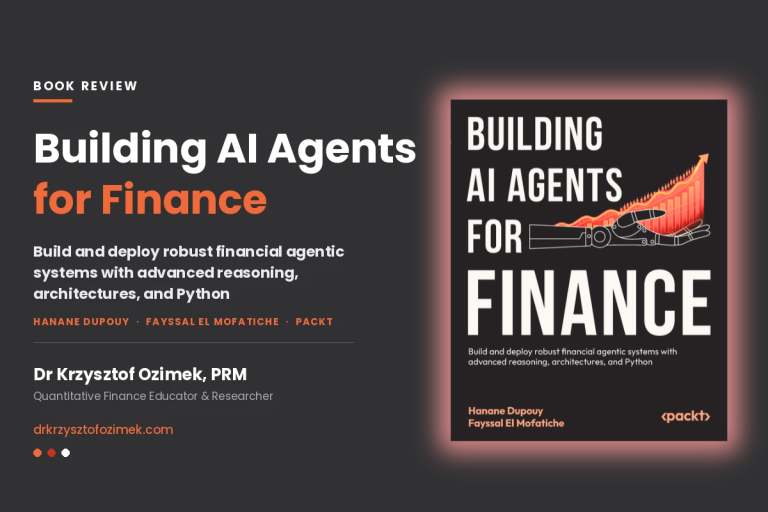
  • Cover of the book Building AI Agents for Finance by Hanane Dupouy and Fayssal El Mofatiche, Packt Publishing, 2026
    Quantitative Finance

    Building AI Agents for Finance, 1st Edition — Book Review

    Dr Krzysztof Ozimek, a Quantitative Investment & Trading Research EducatorDr Krzysztof Ozimek

    Review of Building AI Agents for Finance by Dupouy and El Mofatiche: production-grade multi-agent systems, framework comparison, and compliance-ready evaluation.
    Read More Building AI Agents for Finance, 1st Edition — Book ReviewContinue

  • Bank i Kredyt (Bank and Credit) journal logo with the text Published by the National Bank of Poland, Accepted for publication in a peer-reviewed journal, and the article title Topological Anomalies and Return Predictability in the S&P 500
    Quantitative Finance

    Accepted for Publication in Bank i Kredyt: Topological Anomalies and Return Predictability in the S&P 500

    Dr Krzysztof Ozimek, a Quantitative Investment & Trading Research EducatorDr Krzysztof Ozimek

    Research article on topological anomalies and return predictability in the S&P 500 accepted for publication in Bank i Kredyt. Preprint on arXiv and SSRN.
    Read More Accepted for Publication in Bank i Kredyt: Topological Anomalies and Return Predictability in the S&P 500Continue

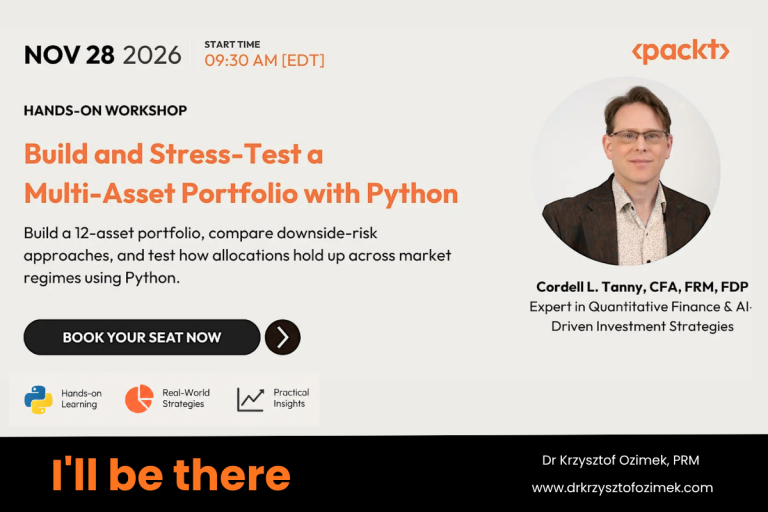
  • Packt banner for the hands-on workshop Build and Stress-Test a Multi-Asset Portfolio with Python with Cordell L. Tanny, November 28, 2026, 09:30 AM EDT, signed by Dr Krzysztof Ozimek with the text I’ll be there
    Quantitative Finance

    Build and Stress-Test a Multi-Asset Portfolio with Python

    Dr Krzysztof Ozimek, a Quantitative Investment & Trading Research EducatorDr Krzysztof Ozimek

    I will attend Cordell Tanny’s live Python workshop on building and stress-testing a 12-asset portfolio with CVaR, clustering and Johnson SU. Nov 28, 2026.
    Read More Build and Stress-Test a Multi-Asset Portfolio with PythonContinue

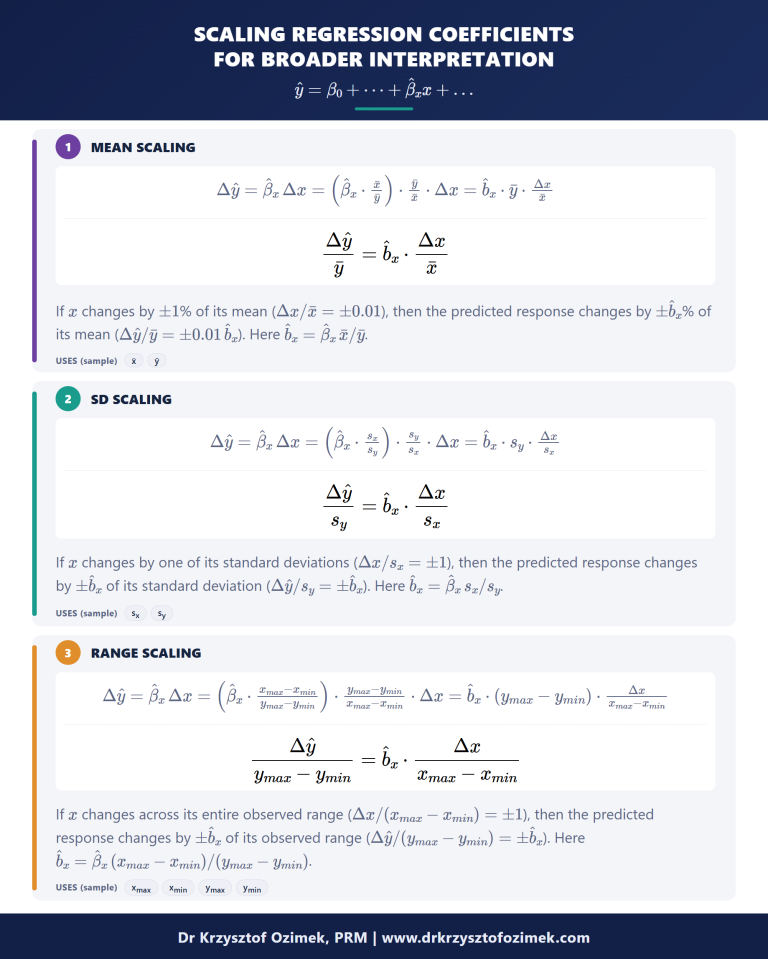
  • Infographic titled Scaling Regression Coefficients for Broader Interpretation, showing the formulas and interpretations for mean scaling, SD scaling and range scaling of a regression coefficient
    Quantitative Finance

    Scaling Regression Coefficients for Broader Interpretation

    Dr Krzysztof Ozimek, a Quantitative Investment & Trading Research EducatorDr Krzysztof Ozimek

    Mean, SD and range scaling turn one fitted regression coefficient into three interpretations, with no re-estimation.
    Read More Scaling Regression Coefficients for Broader InterpretationContinue

  • Book review graphic for Options Pricing with Python, 1st Edition, by Mhamed Bettaieb (Packt), showing the book cover beside the reviewer name and website
    Quantitative Finance

    Options Pricing with Python, 1st Edition — Book Review

    Dr Krzysztof Ozimek, a Quantitative Investment & Trading Research EducatorDr Krzysztof Ozimek

    Review of Options Pricing with Python by Mhamed Bettaieb (Packt): Black-Scholes, trees, Monte Carlo, Greeks and ML, with a teacher’s view of its limits.
    Read More Options Pricing with Python, 1st Edition — Book ReviewContinue

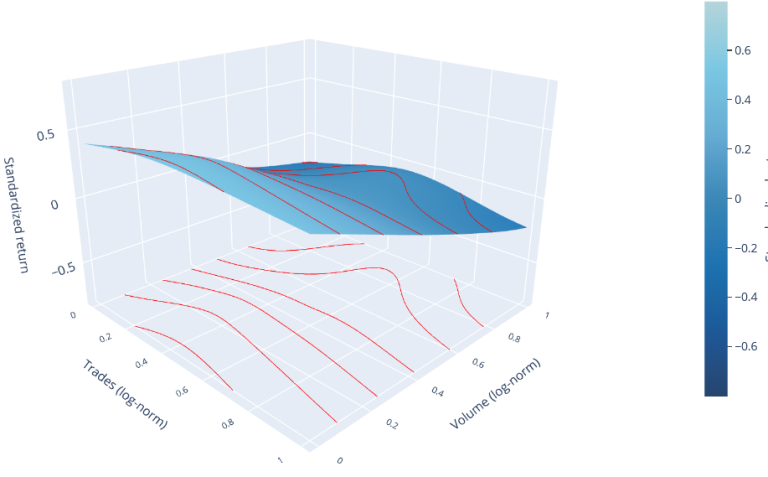
  • Nonlinear intraday return surface showing the interaction between trade count and traded volume.
    Quantitative Finance

    Nonlinear Intraday Return Surface: Trades and Volume Interaction

    Dr Krzysztof Ozimek, a Quantitative Investment & Trading Research EducatorDr Krzysztof Ozimek

    Using 5-minute LOBSTER data for AAPL, this post visualises mean standardised bar returns over a 5×5 grid of jointly ranked trade count and volume. The resulting surface is markedly nonlinear: at 30-second bars volume dominates, while at 60-second bars a diagonal interaction emerges — a pattern inconsistent with purely additive specifications in trades and volume.
    Read More Nonlinear Intraday Return Surface: Trades and Volume InteractionContinue

  • Book review banner for Large Language Models in Finance by Miquel Noguer i Alonso, Packt, with the book cover showing a circuit-board head beside a candlestick chart
    Quantitative Finance

    Large Language Models in Finance, 1st Edition — Book Review

    Dr Krzysztof Ozimek, a Quantitative Investment & Trading Research EducatorDr Krzysztof Ozimek

    Review of Large Language Models in Finance by Miquel Noguer i Alonso (Packt, 2026) from a quant researcher and educator view: backtesting, agents, alpha.
    Read More Large Language Models in Finance, 1st Edition — Book ReviewContinue

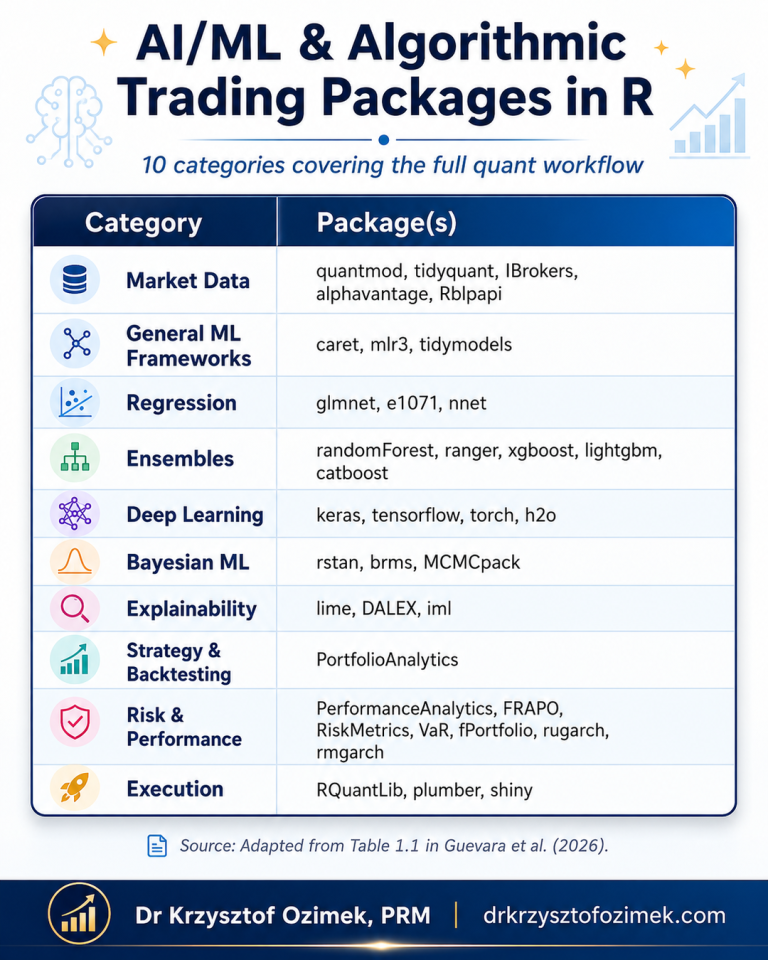
  • Table listing 10 categories of AI/ML and algorithmic trading R packages, from market data to execution
    Quantitative Finance

    AI/ML & Algorithmic Trading Packages in R

    Dr Krzysztof Ozimek, a Quantitative Investment & Trading Research EducatorDr Krzysztof Ozimek

    A quick-reference guide to the R quant stack: 10 categories of AI/ML and algorithmic trading packages covering market data, modeling, risk, and execution.
    Read More AI/ML & Algorithmic Trading Packages in RContinue

  • Promotional banner for the Packt workshop on building GraphRAG applications with Neo4j and LLM agents on September 19, 2026, showing speaker Alessandro Negro, Chief Scientist at GraphAware, with the word Impressions and the name Dr Krzysztof Ozimek, PRM
    Quantitative Finance

    Packt GraphRAG Workshop Impressions

    Dr Krzysztof Ozimek, a Quantitative Investment & Trading Research EducatorDr Krzysztof Ozimek

    My impressions of Packt’s hands-on GraphRAG workshop with Alessandro Negro: Neo4j, LangGraph agents, text-to-Cypher, evaluation, and lessons for quant finance.

    Read More Packt GraphRAG Workshop ImpressionsContinue

Page navigation

1 2 3 … 5 Next PageNext
Disclaimer

All content made available through drkrzysztofozimek.com, including but not limited to digital products, courses, textbooks, articles, and newsletters, is provided for educational purposes only.

We do not provide financial, investment, or trading advice. The information is not intended as a recommendation or solicitation to buy, sell, or hold any financial instrument. You acknowledge that you use the information provided at your own risk.

Eduinn Krzysztof Ozimek shall not be held liable for any loss, damage, or consequences resulting directly or indirectly from reliance on such information.

Eduinn Krzysztof Ozimek

ul. Kryształowa 31/21
01-356 Warsaw
Poland

NIP 526 225 97 76

Telephone: +48 796 594 098
E-mail: contact@drkrzysztofozimek.com

Quantocracy featured quant finance blog badge

  • Terms
  • Privacy Policy
  • Cookie Policy (EU)
  • Contact
  • About
  • Blog
  • Edu Hub
  • Multi-Method VaRCalc
  • Algorithmic Trading Models
  • QuantFin Services

Research

SSRN
arXiv
ORCID

© 2026 Dr Krzysztof Ozimek

Linkedin Facebook YouTube
Manage Consent
To provide the best experiences, we use technologies like cookies to store and/or access device information. Consenting to these technologies will allow us to process data such as browsing behavior or unique IDs on this site. Not consenting or withdrawing consent, may adversely affect certain features and functions.
Functional Always active
The technical storage or access is strictly necessary for the legitimate purpose of enabling the use of a specific service explicitly requested by the subscriber or user, or for the sole purpose of carrying out the transmission of a communication over an electronic communications network.
Preferences
The technical storage or access is necessary for the legitimate purpose of storing preferences that are not requested by the subscriber or user.
Statistics
The technical storage or access that is used exclusively for statistical purposes. The technical storage or access that is used exclusively for anonymous statistical purposes. Without a subpoena, voluntary compliance on the part of your Internet Service Provider, or additional records from a third party, information stored or retrieved for this purpose alone cannot usually be used to identify you.
Marketing
The technical storage or access is required to create user profiles to send advertising, or to track the user on a website or across several websites for similar marketing purposes.
  • Manage options
  • Manage services
  • Manage {vendor_count} vendors
  • Read more about these purposes
View preferences
  • {title}
  • {title}
  • {title}
  • About
  • Contact
  • Blog
  • Books
  • Multi-Method VaRCalc
  • Algorithmic Trading Models
  • QuantFin Services
Search