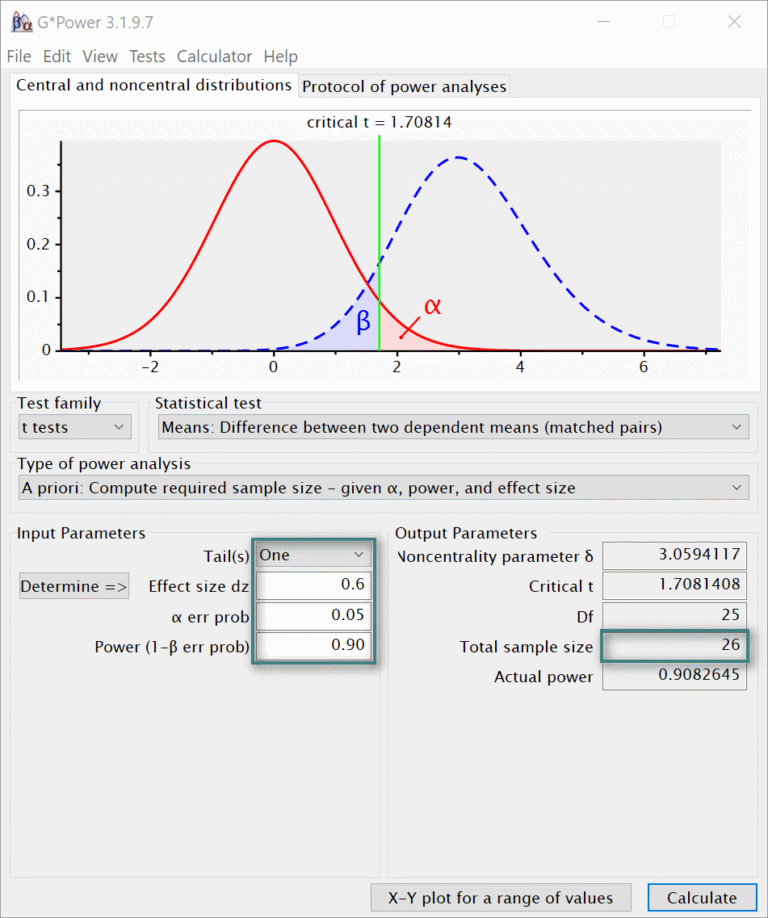
Development of Investment or Trading Strategies with G*Power-like Functionalities
This post explains how G*Power, a tool for statistical power analysis, can be applied to evaluate investment or trading strategies — especially to determine how many observations are needed to detect meaningful performance (e.g., a substantially positive Information Ratio). It demonstrates using a paired-sample t-test in G*Power and replicates the calculation in R and Python, showing how to compute the required sample size to ensure robust strategy validation before deployment.