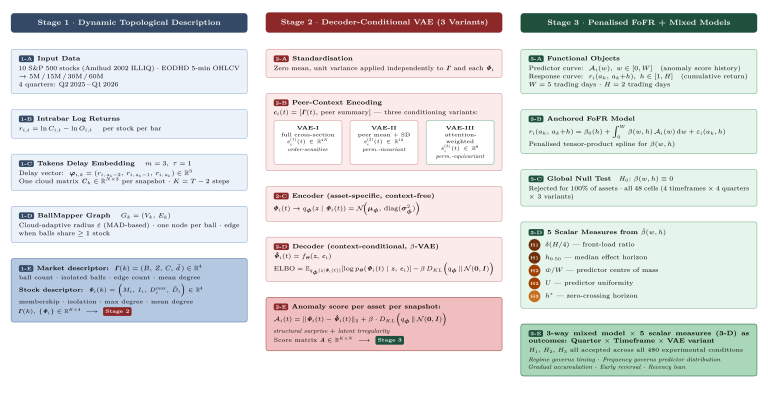
Can the Topological Shape of the Market Predict How Returns Evolve?
I am pleased to announce that my new paper is now available:
“Cross-Sectional Topological Anomaly Scores and Intraday Return Predictability: BallMapper Descriptors, Decoder-Conditional VAE, and Function-on-Function Regression on S&P 500 Intraday Data”