Skip to content
Cropped version of the official logo of Dr Krzysztof Ozimek, representing quantitative finance education and research.
  • About
  • Contact
  • Blog
  • Books
  • Multi-Method VaRCalc
  • Algorithmic Trading Models
  • QuantFin Services
Edu Hub
Cropped version of the official logo of Dr Krzysztof Ozimek, representing quantitative finance education and research.
Dr Krzysztof Ozimek
Edu Hub
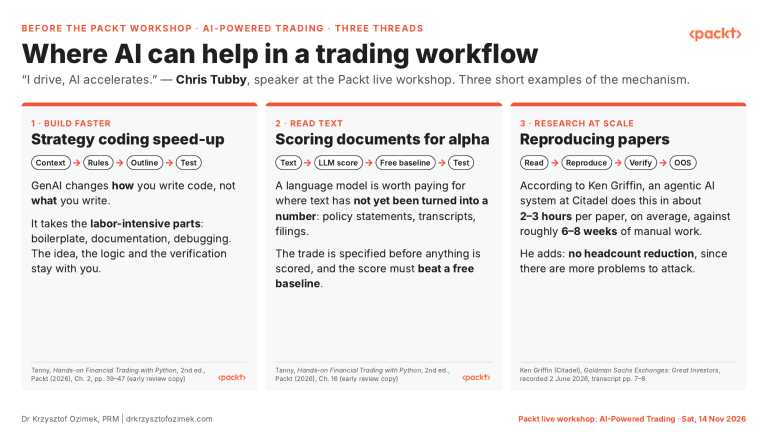
  • Slide titled Where AI can help in a trading workflow with three panels: strategy coding speed-up (context, rules, outline, test), scoring documents for alpha (text, LLM score, free baseline, test) and reproducing papers (read, reproduce, verify, OOS)
    Quantitative Finance

    Where AI Can Help in a Trading Workflow: Three Short Examples
    Dr Krzysztof Ozimek, a Quantitative Investment & Trading Research EducatorDr Krzysztof Ozimek

    Three short examples of where AI helps in a trading workflow: faster strategy coding, scoring text with a language model, and reproducing finance papers.
    Read More Where AI Can Help in a Trading Workflow: Three Short ExamplesContinue

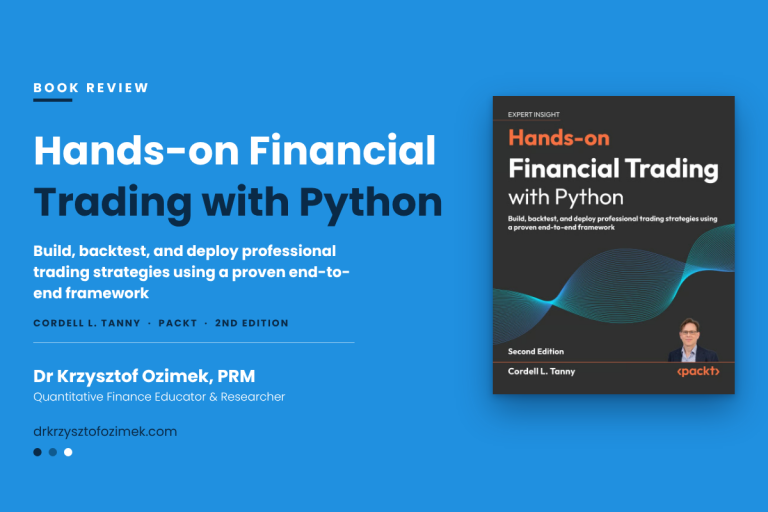
  • Book review cover for Hands-on Financial Trading with Python, 2nd Edition by Cordell L. Tanny (Packt), with the book cover and reviewer Dr Krzysztof Ozimek, PRM
    Quantitative Finance

    Hands-on Financial Trading with Python, 2nd Edition — Book Review

    Dr Krzysztof Ozimek, a Quantitative Investment & Trading Research EducatorDr Krzysztof Ozimek

    Book review of Hands-on Financial Trading with Python, 2nd Edition by Cordell Tanny: a process book on backtest validation, lookahead bias and deployment.
    Read More Hands-on Financial Trading with Python, 2nd Edition — Book ReviewContinue

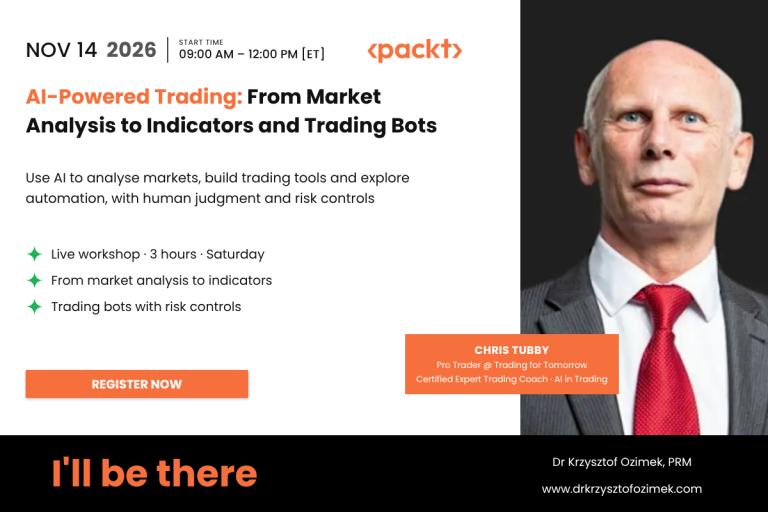
  • Event banner for the Packt live workshop AI-Powered Trading: From Market Analysis to Indicators and Trading Bots, Saturday November 14, 2026, 9:00 AM to 12:00 PM ET, with speaker Chris Tubby and the note I’ll be there from Dr Krzysztof Ozimek
    Quantitative Finance

    AI-Powered Trading Masterclass

    Dr Krzysztof Ozimek, a Quantitative Investment & Trading Research EducatorDr Krzysztof Ozimek

    Live 3-hour online masterclass on Nov 14, 2026 with Chris Tubby: using AI for market analysis, indicators and trading bots, with risk controls.
    Read More AI-Powered Trading MasterclassContinue

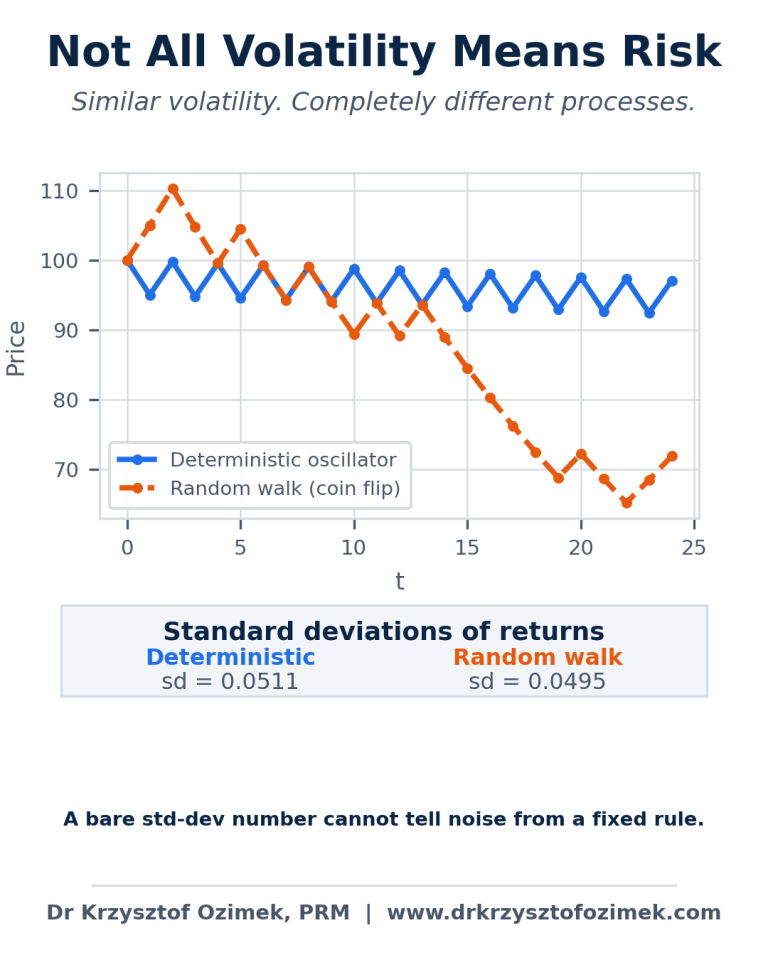
  • Line chart of a deterministic oscillator and a coin-flip random walk, both starting at 100, with nearly equal standard deviations of returns (0.0511 and 0.0495)
    Quantitative Finance

    Not All Volatility Means Risk

    Dr Krzysztof Ozimek, a Quantitative Investment & Trading Research EducatorDr Krzysztof Ozimek

    A deterministic oscillator and a random walk can share almost the same standard deviation. Why sample volatility cannot reveal the process behind a price series.
    Read More Not All Volatility Means RiskContinue

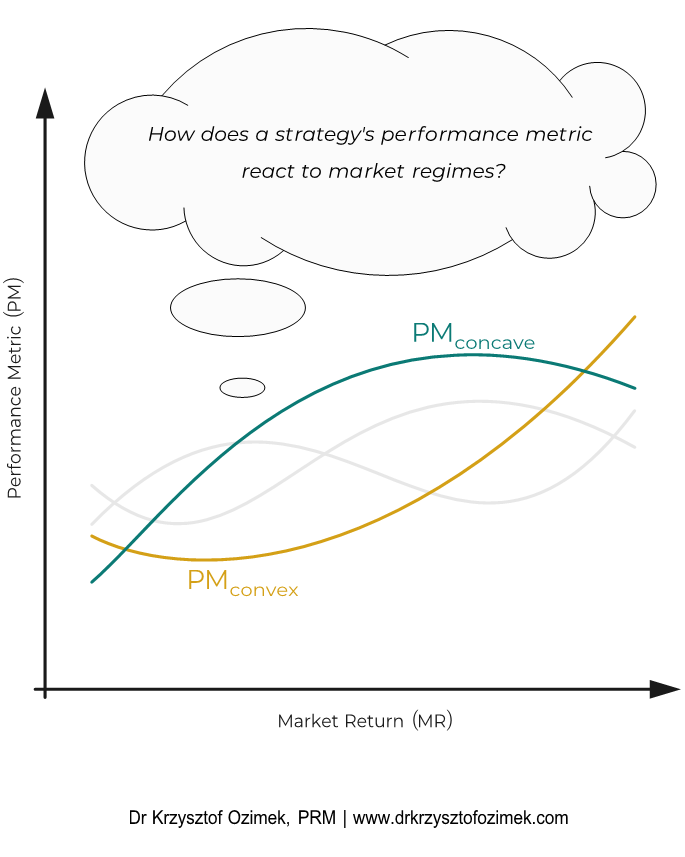
  • Chart of a performance metric (PM) against market return (MR) with a teal concave curve that rises then declines and a gold convex curve that dips then rises, under a thought bubble asking how a strategy’s performance metric reacts to market regimes
    Quantitative Finance

    A Performance Metric Isn’t Just Random: It Can Also Have Shape

    Dr Krzysztof Ozimek, a Quantitative Investment & Trading Research EducatorDr Krzysztof Ozimek

    Does a trading strategy’s performance metric change shape in stressed markets? Convexity and concavity show what the unconditional average hides.
    Read More A Performance Metric Isn’t Just Random: It Can Also Have ShapeContinue

  • Title slide: CVaR isn't just a risk number, the first of three posts before the workshop
    Quantitative Finance

    CVaR Isn’t Just a Risk Number

    Dr Krzysztof Ozimek, a Quantitative Investment & Trading Research EducatorDr Krzysztof Ozimek

    CVaR plays three roles in portfolio work: a risk measure, an input to performance ratios, and a portfolio-construction objective. Part 1 of 3.
    Read More CVaR Isn’t Just a Risk NumberContinue

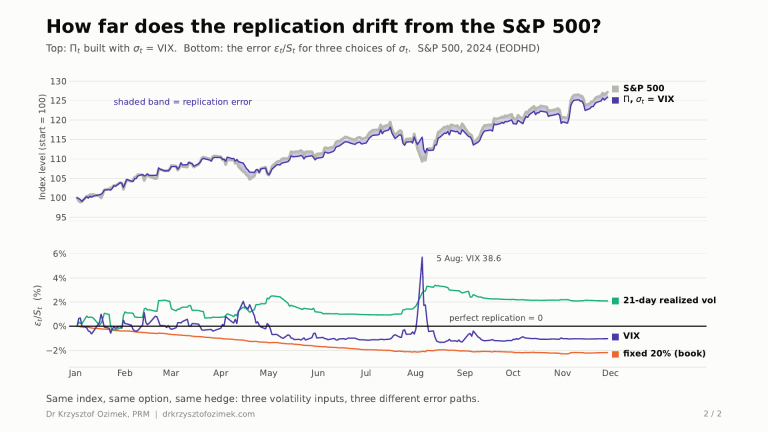
  • Chart of the S&P 500 and the replicating portfolio in 2024 with the replication error for three volatility inputs: fixed 20%, 21-day realized volatility and the VIX, with a spike on 5 August
    Quantitative Finance

    Replication error of the S&P 500 under different volatility measures: just noise, or information?

    Dr Krzysztof Ozimek, a Quantitative Investment & Trading Research EducatorDr Krzysztof Ozimek

    Delta replication of the S&P 500 with options in 2024: how the replication error differs for fixed 20% volatility, 21-day realized volatility and the VIX.
    Read More Replication error of the S&P 500 under different volatility measures: just noise, or information?Continue

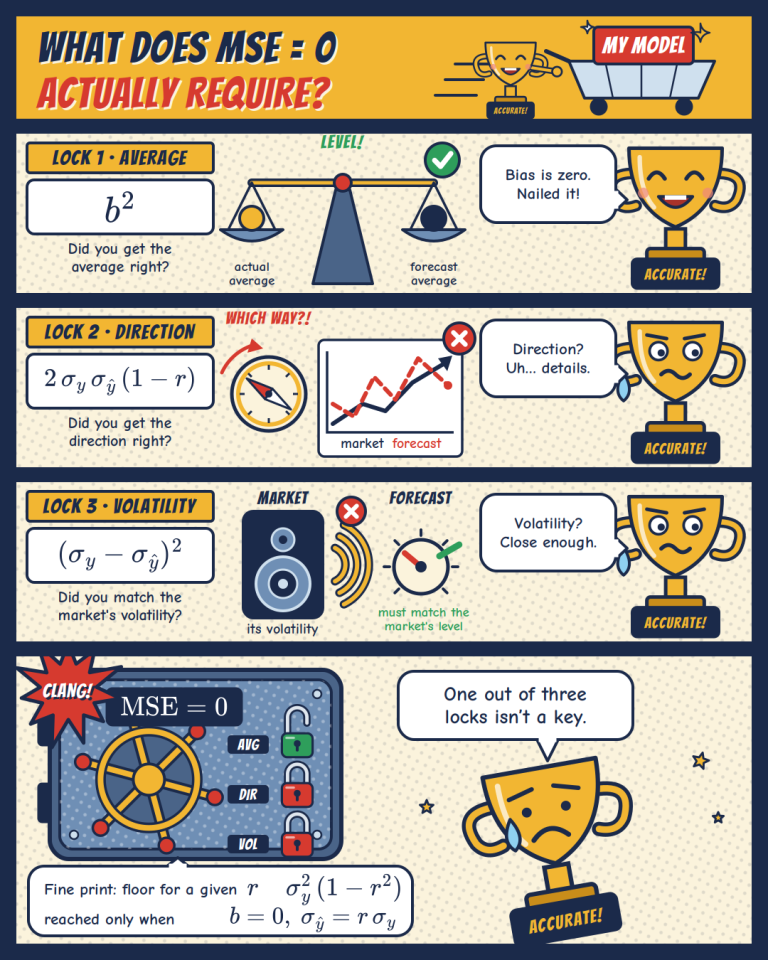
  • Comic-style infographic titled What does MSE = 0 actually require, showing three locks: Lock 1 Average with a level balance scale, Lock 2 Direction with a compass and a forecast line diverging from the market, Lock 3 Volatility with a speaker and a dial; a safe labelled MSE = 0 stays shut with only the average lock open, and a sad trophy says one out of three locks is not a key.
    Quantitative Finance

    What Does MSE = 0 Actually Require?

    Dr Krzysztof Ozimek, a Quantitative Investment & Trading Research EducatorDr Krzysztof Ozimek

    Mean squared error bundles three separate checks: bias, direction and volatility. See the MSE decomposition and why MSE reaches zero only when all three hold.
    Read More What Does MSE = 0 Actually Require?Continue

  • Cover of the book Building AI Agents for Finance by Hanane Dupouy and Fayssal El Mofatiche, Packt Publishing, 2026
    Quantitative Finance

    Building AI Agents for Finance, 1st Edition — Book Review

    Dr Krzysztof Ozimek, a Quantitative Investment & Trading Research EducatorDr Krzysztof Ozimek

    Review of Building AI Agents for Finance by Dupouy and El Mofatiche: production-grade multi-agent systems, framework comparison, and compliance-ready evaluation.
    Read More Building AI Agents for Finance, 1st Edition — Book ReviewContinue

  • Bank i Kredyt (Bank and Credit) journal logo with the text Published by the National Bank of Poland, Accepted for publication in a peer-reviewed journal, and the article title Topological Anomalies and Return Predictability in the S&P 500
    Quantitative Finance

    Accepted for Publication in Bank i Kredyt: Topological Anomalies and Return Predictability in the S&P 500

    Dr Krzysztof Ozimek, a Quantitative Investment & Trading Research EducatorDr Krzysztof Ozimek

    Research article on topological anomalies and return predictability in the S&P 500 accepted for publication in Bank i Kredyt. Preprint on arXiv and SSRN.

    Read More Accepted for Publication in Bank i Kredyt: Topological Anomalies and Return Predictability in the S&P 500Continue

Page navigation

1 2 3 … 6 Next PageNext
Disclaimer

All content made available through drkrzysztofozimek.com, including but not limited to digital products, courses, textbooks, articles, and newsletters, is provided for educational purposes only.

We do not provide financial, investment, or trading advice. The information is not intended as a recommendation or solicitation to buy, sell, or hold any financial instrument. You acknowledge that you use the information provided at your own risk.

Eduinn Krzysztof Ozimek shall not be held liable for any loss, damage, or consequences resulting directly or indirectly from reliance on such information.

Eduinn Krzysztof Ozimek

ul. Kryształowa 31/21
01-356 Warsaw
Poland

NIP 526 225 97 76

Telephone: +48 796 594 098
E-mail: contact@drkrzysztofozimek.com

Quantocracy featured quant finance blog badge

  • Terms
  • Privacy Policy
  • Cookie Policy (EU)
  • Contact
  • About
  • Blog
  • Edu Hub
  • Multi-Method VaRCalc
  • Algorithmic Trading Models
  • QuantFin Services

Research

SSRN
arXiv
ORCID

© 2026 Dr Krzysztof Ozimek

Linkedin Facebook YouTube
Manage Consent
To provide the best experiences, we use technologies like cookies to store and/or access device information. Consenting to these technologies will allow us to process data such as browsing behavior or unique IDs on this site. Not consenting or withdrawing consent, may adversely affect certain features and functions.
Functional Always active
The technical storage or access is strictly necessary for the legitimate purpose of enabling the use of a specific service explicitly requested by the subscriber or user, or for the sole purpose of carrying out the transmission of a communication over an electronic communications network.
Preferences
The technical storage or access is necessary for the legitimate purpose of storing preferences that are not requested by the subscriber or user.
Statistics
The technical storage or access that is used exclusively for statistical purposes. The technical storage or access that is used exclusively for anonymous statistical purposes. Without a subpoena, voluntary compliance on the part of your Internet Service Provider, or additional records from a third party, information stored or retrieved for this purpose alone cannot usually be used to identify you.
Marketing
The technical storage or access is required to create user profiles to send advertising, or to track the user on a website or across several websites for similar marketing purposes.
  • Manage options
  • Manage services
  • Manage {vendor_count} vendors
  • Read more about these purposes
View preferences
  • {title}
  • {title}
  • {title}
  • About
  • Contact
  • Blog
  • Books
  • Multi-Method VaRCalc
  • Algorithmic Trading Models
  • QuantFin Services
Search