
Time Series Bootcamp: Forecasting with ML, Deep Learning, Foundation Models
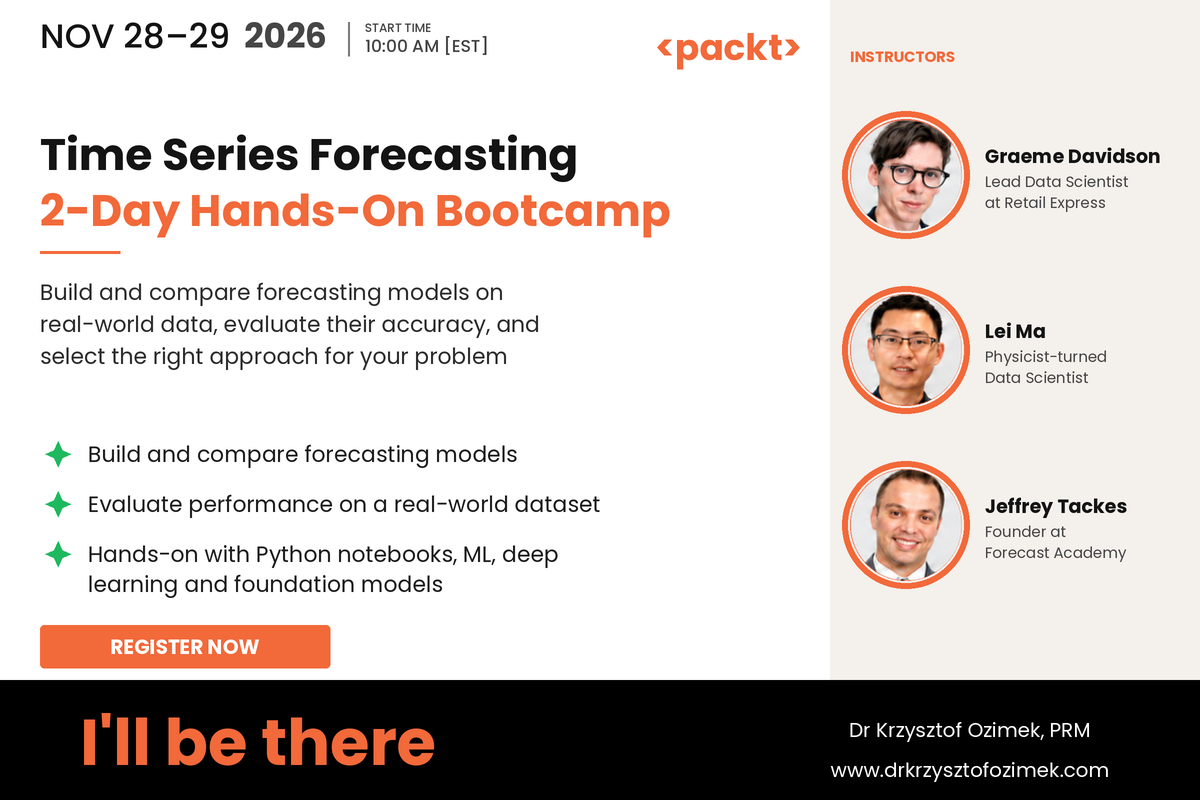
I'll be attending Time Series Bootcamp: Forecasting with ML, Deep Learning, Foundation Models, a live, hands-on online bootcamp by Packt Publishing, on November 28–29, 2026.
10:00 AM – 2:00 PM EST / 4:00 PM – 8:00 PM CET on both days (four hours each).
Which forecasting model should you choose: statistical, machine learning, deep learning, or a foundation model? The bootcamp compares all four on a shared retail dataset, with a common evaluation framework and a shared leaderboard covering accuracy, bias, stability, uncertainty, computational cost, and business impact.
Instructors: Graeme Davidson and Lei Ma, co-authors of "Time Series with PyTorch" (Davidson & Ma, 2026), and Jeffrey Tackes of Forecast Academy, co-author of "Modern Time Series Forecasting with Python", Second Edition (Joseph & Tackes, 2024). Both books are published by Packt.
Day 1: baselines, evaluation, machine learning
- Baselines, evaluation metrics, initial model selection
- Global ML models with MLForecast; exogenous drivers and feature engineering with Nixtla
- Direct vs recursive multi-horizon forecasting
- Objective functions, model optimisation, model selection
- Final leaderboard and Day 2 handoff
Day 2: deep learning, foundation models, uncertainty
- Recap of the Day 1 leaderboard
- Deep learning for global modelling: N-BEATS, N-HiTS, Temporal Fusion Transformers (TFT) vs gradient-boosted decision trees (GBDTs)
- ML vs neural networks: data transformations, features, loss functions
- Labs: default training, hyperparameter optimisation, exogenous variables
- Foundation models: zero-shot vs fine-tuned, covariates, context length, inference costs
- Labs: to fine-tune or not to tune?; hierarchy and forecast coherence
- Uncertainty: proper scoring rules, conformal prediction
- Lab: model selection and ensembling with win rates, Elo, Bradley–Terry rankings
- Final standings across ML, neural networks, foundation models
Tools: StatsForecast, MLForecast, NeuralForecast, TimeCopilot, Chronos-2, TabPFN-TS; reusable notebooks, a GitHub repository, an evaluation harness, a Certificate of Completion.
As a researcher and educator in quantitative finance, I expect to see more clearly how these model families, carried over to the trading domain, can be applied in a supporting role to generate or verify trading signals and to enrich the backtesting process.
Apart from this teaser, I plan three more posts:
- Local vs Global Forecasting Models: One Model per Series, or One for All?
- Foundation Models for Time Series: What They Are and What to Check Before Relying on Them
- a review with my impressions after the bootcamp
Full details and registration: https://www.eventbrite.co.uk/e/time-series-bootcamp-forecasting-with-ml-deep-learning-foundation-models-tickets-2003717845013?aff=Ozimek&discount=OZI40
This link includes a 40% discount (code OZI40), applied automatically at checkout.
Disclosure: I received a complimentary ticket to this event from Packt Publishing. The views above are my own.

Related methodological resources
Continue Exploring Quantitative Finance Methodology
Explore PDF textbooks, implementation-oriented bundles, and methodological frameworks in quantitative investing, trading research, and scientific backtesting.
Explore PDF Textbooks & Bundles